Simple maths for early retirement (FIRE) in the UK
FIRE — financial independence, retire early — popularised the idea that a high savings rate and invested portfolio might let you leave full-time work before State Pension age. The maths can be inspiring; UK tax wrappers and access rules add friction the US-centric blogs often skip.
FinPlanly is educational, not regulated advice. Treat every figure here as an illustration.
The two numbers that matter
Most FIRE frameworks boil down to:
- Annual spending — how much you need per year in today’s money once work is optional.
- Invested assets — pensions, ISAs, taxable accounts, and sometimes rental equity (with caution).
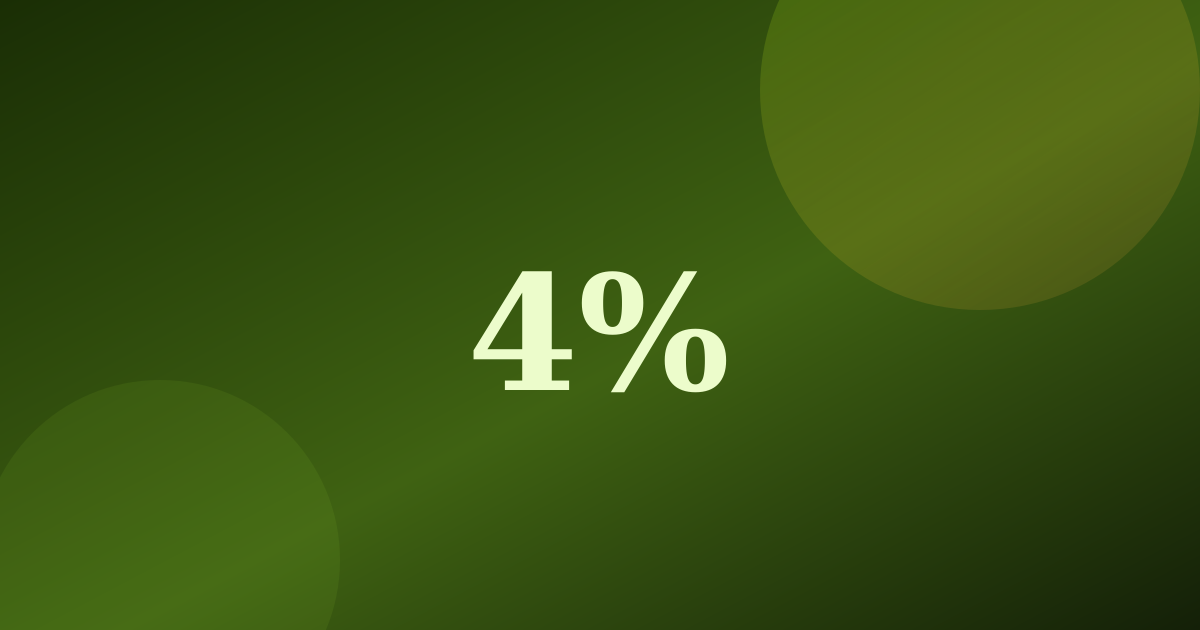
The familiar FIRE number illustration multiplies spending by 25, linked to a 4% withdrawal starting point — see the 4% rule. Early retirees often use more conservative multipliers (30× or 3.3% withdrawals) because timelines stretch longer.
Example for information:
- Spending target £24,000/year → illustration £600,000 invested assets (25×)
- Spending target £36,000/year → illustration £900,000
Add buffers for one-off costs, car replacements, and children if applicable.
Savings rate drives the timeline
Your savings rate — the share of net income you invest — strongly influences years to FI in spreadsheet models. Earning more helps, but spending less relative to income often moves the needle faster because it both increases savings and lowers the target pot.
Illustrative relationship (not individual prediction):
| Savings rate (of take-home) | Rough years to FI in some models* | | --- | --- | | 10% | ~50+ | | 25% | ~32 | | 50% | ~17 | | 65% | ~10 |
\*Assumes consistent real returns and stable spending; real life diverges.
UK access: pensions vs ISAs
Pension pots generally cannot be accessed until minimum pension age (legislation has been moving this upward). If you plan to stop work at 45, you cannot rely solely on pension money for living costs until later unless you bridge the gap.
Common bridge illustrations:
- Cash ISA / Stocks & Shares ISA — flexible withdrawals; annual subscription limits apply.
- Taxable general investment account — use allowances for dividends and capital gains.
- Part-time or consulting income — reduces draw on investments.
- Cash buffer — two to five years of spending in low-risk assets to avoid selling equities in crashes.
Map the timeline: bridge years funded from ISAs/cash, later years from pensions plus State Pension from age 67 (or your forecast age).
State Pension still matters
Even FIRE enthusiasts often receive State Pension eventually if they have a full NI record. That income reduces how much your portfolio must sustain you in later decades — but only from eligibility age onward. Forecast on GOV.UK.
Tax in drawdown
Drawing £40,000 from a pension is not £40,000 spendable — income tax applies beyond personal allowances. ISAs withdraw tax-free. Mixing sources efficiently is tax planning territory; FinPlanly does not provide personalised tax advice.
Housing choices
Paying off the mortgage before FIRE reduces required spending. Downsizing can release capital but is uncertain if you rely on it in models. Renters need long-term rent in spending estimates with inflation sensitivity.
Side FIRE variants
- Barista FIRE — part-time work covers part of expenses; smaller pot needed.
- Lean FIRE — minimal spending; less margin for error.
- Fat FIRE — higher budget; larger pot.
Labels are shorthand; your version should reflect health, family, and location costs.
Behaviour beats spreadsheet precision
Market returns cluster unpredictably. Sequence risk hits early retirees hard. Flexible spending — cutting travel in bad years — improves survival in Monte Carlo illustrations more than chasing an extra 0.1% return.
Run UK-specific scenarios
Use FinPlanly’s retirement plan calculator to plug spending, assets, and retirement age. Compare outcomes when you:
- Delay pension access assumptions
- Add State Pension from a given age
- Lower return estimates by 1–2 percentage points
Sensitivity beats false precision.
Sustainability and ethics
FIRE discussions sometimes ignore career meaning, social security, and inequality. Early retirement is a privilege often built on high income and low dependants’ costs. Plan in a way that respects your mental health and obligations — not only a forum badge.
Healthcare before State Pension age
NHS care remains free at point of use for residents, but dental, optical, and international travel costs rise with age. Budget them explicitly. Private medical insurance is optional and expensive — do not assume FIRE blogs in the US translate directly.
Inflation and spending creep
FIRE models often assume constant real spending. Reality includes lifestyle inflation in good years and compression in bad years. Building 10–15% slack into spending estimates produces more honest FIRE numbers than bare-minimum budgets you will not tolerate for forty years.
One more worked example
Household net spending £2,500/month (£30,000/year) targets a £750,000 illustration at 25×. At a 50% savings rate on £60,000 net household income, you invest £30,000/year. Spreadsheet models might suggest independence in under twenty years if returns cooperate — but childcare, house moves, or career breaks reset the clock. Recompute annually rather than treating one spreadsheet as destiny.
---
*This article is general information for UK readers, not financial advice. FinPlanly is not authorised or regulated by the Financial Conduct Authority. Projections are estimates, not guarantees.*
Model your plan: Retirement plan calculator